Scammers Pretend to Be Grandchildren — Now AI Voice Cloning Makes “Grandparent” Distress Calls Harder to Spot
Grandparent scams use emotional urgency to trick older adults; AI voice cloning now lets fraudsters mimic grandchildren’s voices, increasing losses. Learn how these schemes operate and four practical protections to safeguard seniors and their families.
- “Grandparent” distress calls—scammers impersonate relatives and demand immediate money; see the FBI IC3 PSA.
- AI voice cloning can reproduce a grandchild’s voice from seconds of audio, making calls far more convincing and raising reported losses among older victims.
- Four concrete protections—trusted contacts, withdrawal holds, verification rules, and benefit-change blocks—can reduce risk and stop urgent-payment pressure.
How the distress or “grandparent” scam works
Scammers call older adults pretending to be a grandchild in trouble—often claiming arrest, a crash, or a sudden legal emergency. The caller pushes for secrecy and immediate payment. A second caller commonly follows, impersonating a lawyer, police officer or court official to demand bail, fees or medical costs.
Payment methods are pressured and fast: wire transfers, cash mailed in hidden packages, or pick‑ups by a “courier.” Scammers have even used ride‑share drivers as unwitting money couriers. The pattern—emotional pressure, secrecy, and a tight deadline—is the classic method to short‑circuit good judgment. See the FBI IC3 PSA for details.
AI voice cloning makes the calls more convincing
A growing danger is AI voice cloning. Scammers harvest a short audio clip—from a birthday video, voicemail, or social post—and generate a synthetic voice that can closely match a grandchild. Combined with caller ID spoofing, the result can fool caring relatives.
Law enforcement warns that AI‑enabled scams have driven sharp increases in losses among older adults. Public examples and awareness posts appear on social platforms and agency pages, including an Instagram post and local FBI reports.
Why older adults are targeted — wealth, data and weak checks
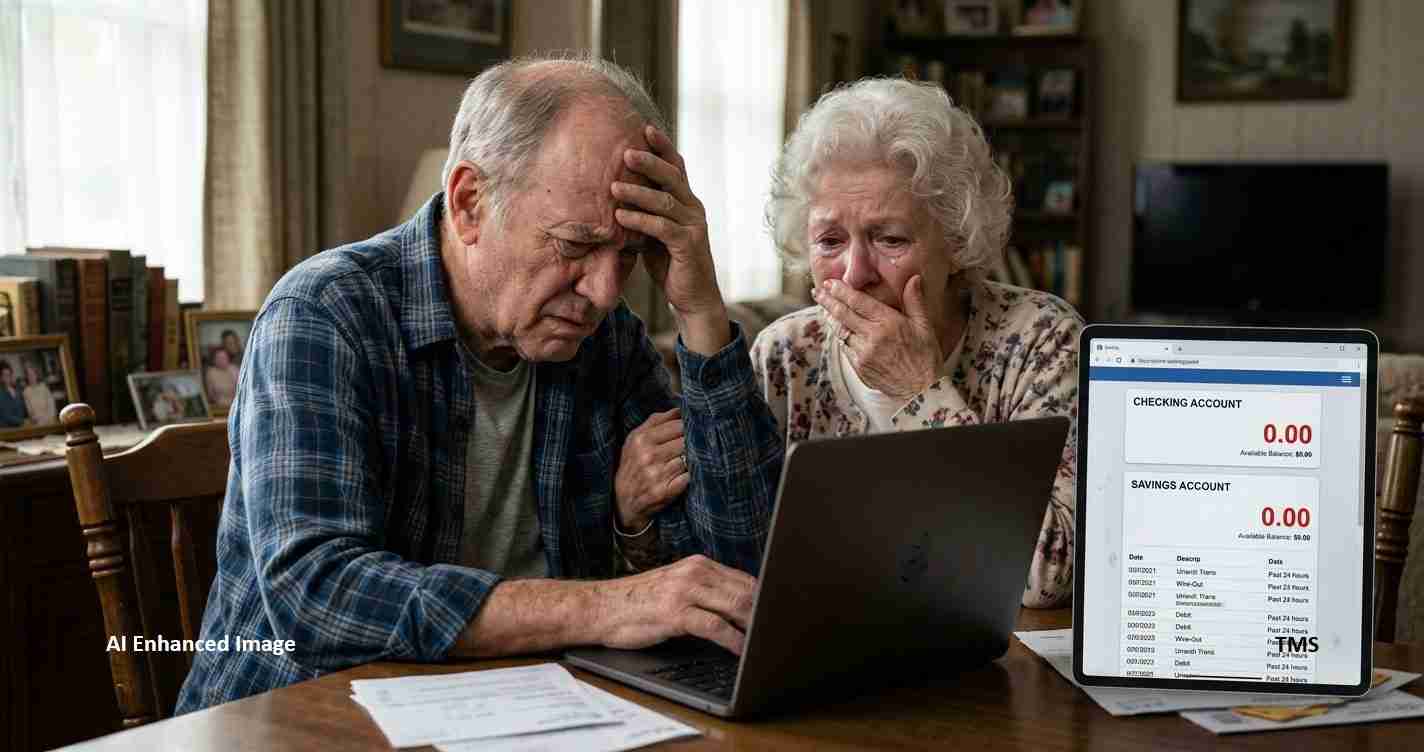
Older Americans are attractive targets: the median net worth for people 65–74 was $409,900 in 2022. Reported average losses for victims 60+ in 2025 were about $38,500 each—far higher than younger victims. Criminals also exploit common identity‑verification fields (date of birth, last four of SSN, mailing address), which have appeared in many breaches.
Large health‑record breaches—affecting Medicaid and employer plans—exposed names, SSNs, birth dates and addresses for millions, making it easier for fraudsters to pass basic checks or open accounts. See consumer alerts from the FBI IC3 PSA for more context.
Under‑reporting hides the real scale
Reported losses understate the problem. Older adults reported $2.4 billion in fraud losses to the Federal Trade Commission in 2024, but the FTC’s report to Congress in December 2025 estimated real losses may have been as high as $81.5 billion for that year. Many victims don’t report crimes due to embarrassment, fear of losing independence, or disbelief that anything can be done—making it harder for law enforcement to spot patterns.
Four practical protections to reduce risk
Families and older adults can take concrete steps now. Start with these four protections recommended by law enforcement and financial experts.
1) Add a trusted contact to brokerage and investment accounts
What it does: A trusted contact lets a broker alert a family member if an account shows signs of fraud or unusual behavior.
How to do it: Call your brokerage or log into account settings and add a trusted contact. This person does not get control of the account but can be contacted to verify suspicious transactions.
2) Ask about holds on suspicious withdrawals
What to ask: Tell banks, brokerages and pension administrators you want safeguards for large or unusual transfers. Ask whether they can place a temporary hold or require extra verification for withdrawals above a set threshold.
Why it helps: A short delay can stop a scammer’s urgent pressure and give time for verification.
3) Verify urgent calls before sending money
Immediate rule: Hang up and call back on a number you know is real—the one on a bank statement or your child’s phone number in your address book.
Use a family code word that only relatives know. If the caller claiming to be a grandchild cannot provide it, treat the call as a scam. Never obey demands to keep the call secret.
4) Block online changes to Social Security and other benefits
Why: With the right personal data, thieves can create or hijack benefit accounts and redirect payments.
Steps: Set up your My Social Security account yourself, ask the Social Security Administration and pension providers for extra verification for online changes, and monitor benefit statements closely. Contact agencies only by published phone numbers or in person—not by numbers or links given in unsolicited calls or texts.
Additional safeguards families should use
- Use strong, unique passwords and a password manager.
- Turn on multi‑factor authentication for email, banks, and benefit accounts.
- Freeze credit records with the major bureaus to stop new accounts from being opened in your name.
- Limit personal details on social media—birthdays, addresses and family names can fuel scams.
- Report attempts to the FBI Internet Crime Complaint Center (IC3), the FTC, local police, and your state attorney general to help authorities track and prosecute fraud.
Implications for Las Vegas
Economic impact: Las Vegas has a large retiree community and many older residents who hold retirement savings and pensions. Higher median savings among older adults means local victims could lose substantial sums, affecting household budgets and local consumer spending.
Political consequences: Local officials, including the Nevada attorney general and Clark County leaders, may face pressure to expand elder‑fraud prevention programs, require stronger bank protections, and support public awareness campaigns.
Social effects: Victims often feel shame and withdraw from social contacts. In Las Vegas, where community centers and senior programs are key social hubs, scams can increase isolation and strain local support networks.
Practical applications: Local banks, credit unions and retirement plan administrators should be urged to offer trusted contact designations, hold policies, and extra verification steps for large transfers. Seniors and families should set up My Social Security accounts, freeze credit, and consult local law enforcement and the Nevada attorney general’s consumer protection office for resources.
Sources and further reading
- FBI Internet Crime Complaint Center (IC3) public safety advisory
- FBI awareness posts and local examples
- Public example of AI/voice alert (Instagram)
- Illustrative video on scams and elder fraud
- Federal Trade Commission consumer information and reports
If you or a family member receives a call asking for urgent money, hang up, verify, and contact local authorities and your financial institutions before you act.